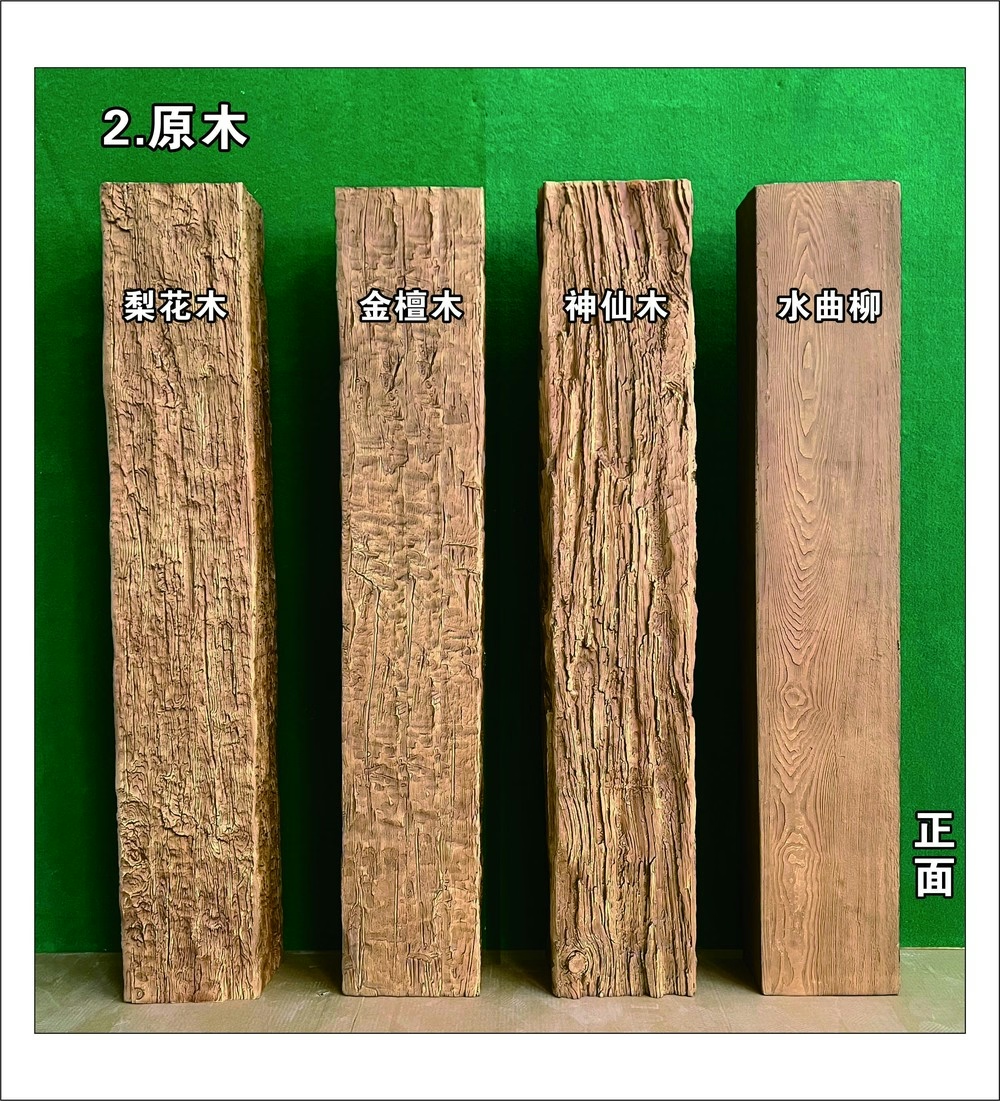
The hotel renovation contract looked like a career breakthrough—$85,000 for beam installation across six floors representing my largest project to date. Two weeks before start date, the general contractor's compliance check revealed a problem: my residential contractor license didn't qualify for commercial work over three stories in that jurisdiction. Obtaining the required commercial license would take 6-8 weeks including examination and bonding requirements I didn't currently meet. The project couldn't wait—they hired another contractor with proper commercial credentials while I watched my big opportunity disappear. That painful lesson taught me that contractor licensing and insurance requirements vary dramatically between residential and commercial work, and crossing that threshold demands preparation beyond just having installation skills.
Understanding licensing requirements, insurance thresholds, and bonding obligations allows contractors to pursue commercial opportunities legally and professionally. These administrative requirements create barriers to entry but also protect qualified contractors from undercapitalized competitors who cannot meet legitimate business standards.
Contractor License Classifications and Trade Scope
General contractor licenses cover broad construction work including multiple trades, typically required for projects exceeding specified dollar thresholds ($500 in some states, $50,000+ in others). Beam installation as part of comprehensive renovation might require general contractor licenses even though beam work alone wouldn't trigger requirements. Scope determination proves critical—understand whether proposed work constitutes general contracting or specialty trade falling under different license classifications.
Specialty contractor licenses for specific trades—carpentry, finish carpentry, or specialty ceiling contractors—may cover decorative beam installation depending on jurisdiction definitions. Some states classify beam work as finish carpentry requiring carpentry contractor licenses. Others consider it specialty ceiling work under acoustic and specialty ceiling contractor classifications. Research specific jurisdiction requirements rather than assuming your existing licenses cover new work types.
Residential versus commercial license distinctions exist in many jurisdictions. Residential contractor licenses may limit work to single-family and small multi-family projects under certain sizes or values. Commercial licenses cover larger buildings, different occupancy types, and higher project values. These commercial licenses typically require greater financial resources, more extensive examination, and higher insurance coverage than residential licenses.
The monetary thresholds triggering license requirements vary dramatically by jurisdiction. Some states require licenses for any work over $500, while others set minimums at $10,000, $25,000, or higher. These thresholds may measure single project value, annual aggregate work, or other metrics. Understand specific threshold definitions since they determine whether your business scale requires licensing or operates below threshold exemptions.
Unlicensed practice penalties range from administrative fines ($500-5,000 per violation) through misdemeanor or felony criminal charges in serious cases. Contractors working without required licenses cannot enforce contracts through courts—clients can refuse payment and contractors have no legal recourse. This legal vulnerability makes proper licensing essential business protection beyond just compliance with administrative requirements.
Commercial Insurance Coverage Requirements
Commercial general liability (CGL) insurance covers third-party bodily injury and property damage claims arising from business operations. Minimum coverage for commercial contracting typically starts at $1 million per occurrence / $2 million aggregate, with many projects requiring $2M/$4M or $5M/$10M limits. These limits substantially exceed residential contractor insurance where $500K/$1M often suffices. Higher limits cost more—figure $2,500-5,000 annually for $1M/$2M coverage, scaling upward with higher limits.
Workers' compensation insurance covers employee injuries regardless of fault, required in most states for businesses with employees. Requirements vary—some states mandate coverage with first employee, others exempt businesses under certain size thresholds, and some allow sole proprietors to opt out. Commercial projects typically require proof of workers comp even if state law would otherwise exempt—expect $8,000-15,000 annually depending on employee count and job classification risk factors.
Commercial auto insurance covers vehicles used for business with higher limits than personal auto policies. Commercial projects often require minimum $1 million combined single limit auto coverage. If using personal vehicles for business, personal auto policies may not cover commercial use—verify coverage or obtain commercial auto policies preventing coverage gaps that could leave you exposed to claims your insurance won't cover.
Professional liability or errors and omissions (E&O) insurance covers claims arising from professional advice, design decisions, or alleged negligence in professional services. While not universally required for installation contractors, design-build projects or work involving layout and design decisions may trigger E&O requirements. This specialized coverage costs $1,500-4,000+ annually depending on practice scope and coverage limits.
Builders risk insurance covers property during construction from damage or loss. Project owners typically carry this coverage, but contractors sometimes must provide it or carry separate installation floater coverage protecting materials and work-in-progress. Clarify responsibility for builders risk coverage in contract documents before assuming someone else carries it—gaps in coverage leave parties exposed to uninsured losses.
Bonding Requirements and Capacity
Bid bonds guarantee contractors will honor bid prices and enter contracts if awarded projects. Public sector projects typically require bid bonds equal to 5-10% of bid amounts. These bonds protect owners from contractors bidding then withdrawing, forcing re-bidding at potentially higher costs. Obtaining bid bonds requires pre-qualification with surety companies evaluating financial capacity and track record.
Performance bonds guarantee project completion per contract terms. If contractors default, surety companies either complete work or compensate owners for completion costs. Public projects typically require 100% performance bonds—$500,000 project requires $500,000 performance bond. Large private projects increasingly require performance bonds protecting against contractor failure mid-project.
Payment bonds guarantee subcontractors and suppliers receive payment for work and materials provided. These bonds protect lower-tier parties from general contractor or prime contractor payment failures. Public projects typically require payment bonds equal to project value. The bonding protects project owners from mechanics liens and ensures all parties contributing to projects receive proper compensation.
Bonding capacity represents the maximum dollar value of work surety companies will bond for specific contractors. This capacity depends on financial strength, track record, and current work backlog. Starting contractors might qualify for $100,000-250,000 capacity while established firms might achieve $5M-50M+ capacity. Projects requiring bonds exceeding contractor capacity become unbiddable regardless of technical capability to perform work.
The surety underwriting process examines contractor financial statements, work history, references, and current commitments. Companies with weak financial positions, limited track records, or poor payment histories struggle to obtain bonding at any cost. Strong financials, solid track records, and professional reputation command favorable bonding rates (0.5-2% of project value) while marginal applicants pay higher rates or face rejection.
Jurisdiction-Specific Variations and Compliance
State licensing requirements vary dramatically—California requires licenses for work over $500, while Texas has no state-level contractor licensing (though local jurisdictions may impose requirements). Some states mandate rigorous examinations demonstrating trade knowledge and business competency. Others require only financial responsibility and basic criminal background checks. Research specific state requirements rather than assuming other-state experience translates directly.
Local licensing beyond state requirements exists in many jurisdictions. Cities and counties may impose additional contractor registration, permit requirements, or business licenses beyond state-level licensing. Major cities often maintain separate contractor licensing or registration programs that state licenses don't satisfy. Budget time and cost for multiple jurisdiction compliance when working across geographic areas.
Reciprocity agreements between states allow licensees in one state to obtain licenses in others through expedited processes. Contractors licensed in reciprocity states can demonstrate that qualification to streamline licensing in partner states. However, reciprocity is not universal—many states maintain independent processes requiring separate examinations and qualifications regardless of other-state credentials.
Registration and reporting requirements for out-of-state contractors working in jurisdictions maintain compliance when performing projects outside home states. These registrations often require posting bonds, appointing resident agents, and maintaining records accessible to jurisdiction authorities. Ignoring these requirements creates legal vulnerability—contracts become unenforceable and administrative penalties can apply.
Continuing education requirements maintain license validity in many jurisdictions. Contractors must complete specified hours of approved education annually or biannually covering code updates, safety training, business management, or trade skills. Track CE requirements and complete necessary education before renewal deadlines—expired licenses prevent bidding or contracting until reinstated.
Risk Management and Loss Prevention
Safety programs demonstrating commitment to accident prevention improve insurance rates and reduce claims. Written safety plans, regular toolbox talks, proper personal protective equipment programs, and incident investigation procedures document systematic safety management. Insurers and project owners increasingly demand documented safety programs particularly on larger commercial projects.
Claims history management involves prompt reporting, thorough investigation, and aggressive defense or fair settlement of claims. Excessive claims increase insurance premiums through experience modification factors—multipliers applied to base rates reflecting individual claim history. Contractors with clean records pay significantly less than those with multiple claims even if base coverage and limits match.
Subcontractor compliance verification ensures subs carry adequate insurance and licensing before allowing them on projects. General contractors face liability for unlicensed or uninsured sub actions even when unaware of non-compliance. Certificate tracking systems, license verification, and contract provisions requiring maintained compliance protect GCs from sub-created liability.
Contract review before signing identifies and negotiates problematic provisions creating uninsurable risk. Unlimited liability clauses, indemnification of owner for owner's negligence, waiver of consequential damage exclusions, and other one-sided terms create exposures insurance won't cover. Negotiate balanced contract language or reject contracts creating unreasonable risk regardless of project attractiveness.
Compliance Verification and Documentation
Pre-qualification documentation packages assembled before pursuing projects streamline proposal and contracting processes. These packages include license copies, insurance certificates, bond capacity letters, financial statements, references, safety records, and prior project examples. Organized professionals with complete documentation ready to provide impress clients and facilitate contracting versus scrambling to assemble documentation after project awards.
The certificate of insurance (COI) format and content prove critical for project acceptance. COIs must name project owners as additional insureds, list correct coverage types and limits, identify projects, and include proper contact information. Many submissions get rejected for incomplete or incorrect COIs requiring reissuance—delaying project starts. Use experienced insurance agents who understand commercial COI requirements preventing rejection.
License verification processes confirm contractor credentials are current and valid. Project owners or their representatives check license status with issuing authorities, verify there are no disciplinary actions, and confirm coverage for proposed work types. Maintain current licenses and address any issues immediately—projects discovering license problems mid-work create crisis requiring rapid correction.
Renewal tracking systems prevent inadvertent license or insurance lapses. Calendar reminders 60-90 days before expiration dates allow completing renewals without last-minute crisis. Automated insurance renewal usually works smoothly, but license renewals requiring CE completion or examination need advance attention. Treat these renewals as critical business priorities preventing coverage gaps.
Strategic Considerations for Market Entry
The market entry decision into commercial work requires assessing whether your business scale justifies compliance investments. If residential work fully utilizes capacity and generates adequate profits, commercial expansion may not make economic sense despite apparent opportunities. However, contractors hitting residential market ceilings may find commercial markets provide growth avenues justifying investment in elevated compliance capabilities.
Staged compliance building allows progressive market entry rather than attempting immediate full commercial capability. Perhaps obtain commercial licenses but maintain modest insurance limits pursuing smaller commercial projects initially. As experience and financial capacity grow, increase bonding capacity and insurance limits pursuing larger work. This staged approach manages risk and investment while building toward full commercial capability over time.
Partnership or joint venture approaches allow accessing commercial markets by teaming with established commercial contractors providing licenses, bonding, and insurance while you contribute trade skills and labor. These arrangements provide commercial experience and track record building toward independent commercial capability. Choose partners carefully—joint ventures create shared liability requiring absolute confidence in partner competency and integrity.
The specialization strategy focuses on niches where you can achieve competitive advantages rather than competing across broad commercial markets. Perhaps target hospitality beam installation where you've developed reputation and references, rather than pursuing general commercial work where you compete against established firms with decades of experience. Specialization allows building dominant positions in focused markets rather than struggling as marginal players in broad markets.

Contractor licensing and insurance requirements represent administrative barriers to commercial market entry but also professional standards separating legitimate established contractors from marginal operators. Understanding and meeting these requirements opens commercial opportunities while protecting businesses from legal exposure that non-compliance creates. The investment in proper licensing, adequate insurance, and bonding capacity proves substantial but necessary for contractors pursuing commercial work where project scale and client sophistication demand professional business infrastructure beyond what residential work typically requires. Building this capability strategically rather than reactively positions contractors for sustainable growth into commercial markets that reward professionalism and penalize inadequate business foundation regardless of technical craft skill.
Technical References
ASTM standards cited in every specification
Test Data
Lab results from internal testing program
Updated 2026
Reviewed against current product specs